Health Insurance Claim Process
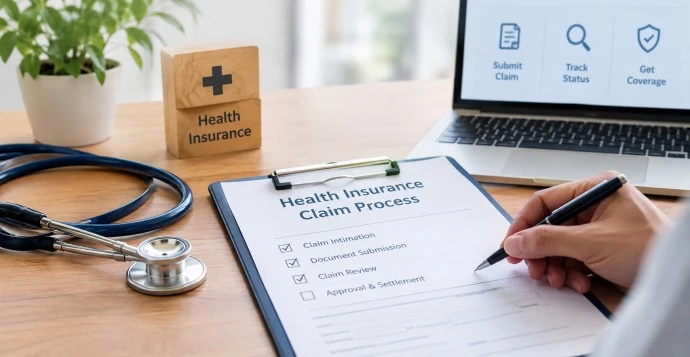
Health Insurance Claim Process
A health insurance policy is most useful when you know how to make a claim when you actually need it. Many people understand the premium and coverage but become unsure when the hospital asks for a pre-authorization form, documents, or claim intimation.
The health insurance claim process is the procedure you follow to inform your insurer about a medical treatment and request payment or reimbursement according to your policy. In India, health insurance claims are generally handled in two ways: cashless claims at network hospitals and reimbursement claims where you pay the hospital first and claim the eligible amount later.
The process itself is not complicated. The key is knowing when to inform the insurer, which documents to keep, and what your policy actually covers.
How to Check Health Insurance Claim Status?
You can usually check your health insurance claim status online through your insurer's website or mobile app. Keep your claim number, policy number, or registered mobile number ready, as the details required can vary between insurers.
Steps to Check Your Health Insurance Claim Status
- Visit your insurer's official website or app.
- Go to the “Track Claim” or “Claim Status” section.
- Enter your claim number, policy number, or registered mobile number, as requested.
- Complete the OTP or other verification process.
- Check the latest update on your health insurance claim status.
Some insurers also send claim updates through SMS or email during different stages of the claim. For example, HDFC ERGO provides online claim tracking and status updates through registered communication channels.
Types of Health Insurance Claims
There are two main types of health insurance claims you should know about.
1. Cashless Health Insurance Claim
A cashless claim allows you to receive treatment at a network hospital without paying the entire eligible hospital bill upfront. The insurer settles the approved amount directly with the hospital, while you pay expenses that are not covered, such as applicable co-payment, deductions or inadmissible items.
2. Reimbursement Health Insurance Claim
In a reimbursement claim, you generally pay the hospital expenses yourself and then submit the required documents to the insurer for reimbursement of the admissible amount. This option can be relevant when treatment is taken at a non-network hospital or when cashless treatment is not available or approved.
How Does the Cashless Health Insurance Claim Process Work?
Here is the process in simple steps.
Step 1: Check the Network Hospital
For cashless treatment, first check whether the hospital is part of your insurer's current network. You can usually find the network hospital list on the insurer's website, app or customer support channel. IRDAI also says insurers should provide information about empanelled hospitals and their claim procedures.
Step 2: Inform the Insurer
For planned hospitalization, inform the insurer within the timeline mentioned in your policy. For an emergency, notify the insurer as soon as reasonably possible and follow the applicable policy procedure. Timelines can vary by insurer and policy, so don't assume that one company's deadline applies to every policy.
Step 3: Submit the Pre-Authorization Request
The hospital's insurance or TPA desk generally helps submit the cashless pre-authorization request to the insurer. The request may include the patient's details, diagnosis, proposed treatment, estimated expenses and relevant medical reports.
Step 4: Wait for the Approval
The insurer reviews the request and decides whether cashless treatment can be authorized under the policy. Importantly, cashless approval does not necessarily mean that every hospital expense will be paid. Items outside the policy, applicable deductions, co-payments and other non-payable expenses may still have to be paid by you.
Step 5: Treatment and Discharge
Once treatment is completed, the hospital sends the final bills and required documents to the insurer or TPA. The insurer reviews the final claim and settles the approved amount directly with the hospital.
How Does the Reimbursement Claim Process Work?
The reimbursement process is slightly different.
Step 1: Inform Your Insurer
Notify the insurer about the hospitalization within the applicable timeframe. Don't wait until after discharge if your policy requires prior intimation.
Step 2: Pay the Hospital Bill
You generally pay the hospital and collect the relevant bills, receipts and medical documents.
Step 3: Collect All Documents
Ask the hospital for the discharge summary, final bill, prescriptions, investigation reports and other documents relating to the treatment.
Step 4: Submit the Claim
Complete the reimbursement claim form and submit it with the required documents through the insurers prescribed online or offline process.
Step 5: Claim Verification
The insurer reviews the medical records, bills and policy coverage. It may ask for additional information if something is missing or needs clarification.
Step 6: Reimbursement
If the claim is admissible, the approved amount is paid to the policyholder or eligible claimant according to the policy process. For example, HDFC ERGO currently states that reimbursement claims are processed within 15 days after satisfactory receipt of the last required document, subject to its terms and conditions.
Documents Required for a Health Insurance Claim
The exact list can differ between insurers and policies, but you should generally keep these documents ready:
- Health insurance card/e-card
- Policy number
- Duly completed claim form
- Photo ID
- Doctor's prescription
- Hospital admission advice
- Discharge summary
- Final hospital bill
- Detailed bill breakup
- Payment receipts
- Pharmacy bills and prescriptions
- Diagnostic and investigation reports
- Medical reports
- Bank/NEFT details where required
- FIR/MLC in applicable accident cases
- Any additional document requested by the insurer
IRDAI guidance advises policyholders to keep important medical papers, prescriptions, discharge summaries, investigation reports, bills and receipts.
One practical tip: Take clear copies or digital scans of everything before handing over original documents.
How Long Does a Health Insurance Claim Take?
This is one of the most searched questions about health insurance claims. Under IRDAI's current health insurance guidance, the stated turnaround times include:
- Cashless pre-authorization: decision within 1 hour of receiving the request
- Final cashless authorization: within 3 hours of receiving the discharge authorization request
- Other-than-cashless claims: 15 days
These are regulatory TAT norms, but the actual handling of a particular claim can depend on whether the required information and documents have been received and whether further verification is needed.
So, if your claim is taking longer than expected, first check whether the insurer has raised a document or information requirement.
Why Can a Health Insurance Claim Be Rejected?
A claim isn't rejected simply because you have health insurance. The treatment and claim still have to meet the policy conditions.
Common reasons for claim disputes or rejection can include:
- Treatment falling under a policy exclusion
- Waiting period not completed
- Non-disclosure of relevant pre-existing conditions
- Policy being inactive
- Expenses exceeding applicable limits
- Non-payable or excluded expenses
- Incorrect or incomplete documents
- Treatment not meeting the policy's definition of a covered event
- Fraudulent or misleading information
This is why it is better to read your policy wording before a medical emergency happens, rather than trying to understand every condition while you are already in the hospital.
Care Health Insurance, for example, specifically advises policyholders to disclose pre-existing conditions, submit required documents and follow the insurer's claim-intimation procedure to reduce the chances of delays or rejection.
What If Your Health Insurance Claim Is Rejected?
Don't immediately assume that the decision cannot be questioned.
First, ask the insurer for the specific reason for rejection. Check the rejection letter or claim communication against your policy wording.
If you believe the decision is incorrect, you can raise the issue through the insurer's grievance process. If the matter remains unresolved, IRDAI's Bima Bharosa platform provides a mechanism for registering insurance complaints.
Keep your claim number, policy documents, medical records and insurer communications together. It makes the grievance process much easier.
Cashless vs Reimbursement: What's the Difference?
Feature | Cashless Claim | Reimbursement Claim |
Hospital | Usually network hospital | Can apply to eligible non-network treatment |
Initial payment | Eligible amount generally settled with hospital | You pay first |
Pre-authorization | Required for cashless treatment | Generally not the same process |
Main paperwork | Pre-authorization + medical documents | Claim form + bills + medical documents |
Convenience | Less upfront financial burden | More upfront payment |
Final payment | Insurer settles approved amount with hospital | Approved amount reimbursed to claimant |
The important thing to remember is that cashless does not mean completely free treatment. You may still have to pay exclusions, co-payments, deductibles and other non-payable expenses.
How to Make Your Health Insurance Claim Process Easier
A few simple habits can save you a lot of trouble later. Keep your policy details accessible. Save your insurer's customer-care number and keep your e-card on your phone. Check the network hospital list before planned treatment. Don't assume that every nearby hospital provides cashless treatment.
Inform the insurer on time. Delayed intimation can create unnecessary complications. Keep every medical document. Even a small prescription or investigation report may become relevant during claim assessment.
Read the deductions carefully. If the final approved amount is lower than the hospital bill, ask for the reason rather than simply accepting the difference.
Never hide medical information. Incorrect or incomplete information can create problems during claim assessment.
FAQs
Can I claim health insurance for treatment at any hospital?
It depends on your policy. Cashless treatment generally requires a network hospital, while eligible reimbursement claims may be possible for treatment at other hospitals according to the policy terms.
Can I claim pre-hospitalization and post-hospitalization expenses?
Yes, if your policy covers them. The number of days and eligible expenses depend on the specific policy. Keep prescriptions, diagnostic reports and payment receipts for these expenses.
Can I have two health insurance policies and claim from both?
Yes, but the process depends on the type of policies and the nature of the claim. For indemnity-based policies, IRDAI states that you can choose one insurer as the primary insurer, with coordination between insurers where additional coverage is needed, subject to policy conditions.
Does cashless approval guarantee full claim settlement?
No. Cashless approval is subject to the policy terms and final claim assessment. Non-covered expenses, co-payments, deductibles and applicable deductions may still be payable by you.
What should I do if the insurer asks for additional documents?
Submit the requested documents as soon as possible and keep proof of submission. Delays often happen when the insurer is waiting for information needed to assess the claim.

5.0
Need advice from experts?
Health is tricky, and insurance trickier. But we'll simplify it for you — for FREE! Book a call now. Limited slots available!
 Talk to an Advisor
 Talk to an Advisor