Can You Surrender Term Insurance? Rules and Process
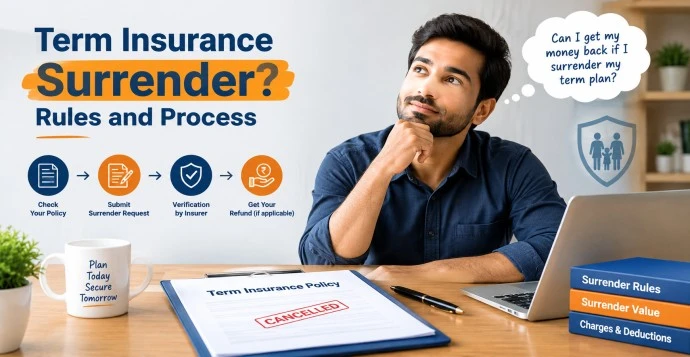
Can You Surrender Term Insurance? Rules and Process
Yes, a term insurance policy can generally be surrendered if the policy terms allow it. However, surrendering a pure term plan usually does not mean you will receive a refund of the premiums you have already paid.
In a term insurance surrender, you voluntarily end the policy before its scheduled maturity. However, a standard pure-term insurance policy generally provides only life cover and does not accumulate a surrender value. Some plans, particularly policies with a Return of Premium feature, may have a surrender benefit based on the policy terms.
Before surrendering your policy, it is important to understand the surrender rules, possible refund, charges, and what happens to your life cover after cancellation.
What Is Term Insurance Surrender?
Term insurance surrender means voluntarily ending your policy before the end of its policy term. For example, suppose you purchased a 30-year term insurance policy but later decide that you no longer need the cover. Instead of continuing the policy until its scheduled end, you can ask the insurer to terminate it according to the applicable policy conditions.
Once the surrender is processed, the life cover normally ends. This means your nominee will not receive the policy's death benefit for an event occurring after the policy has been surrendered.
This is different from simply stopping premium payments. Non-payment can result in a policy becoming lapsed or otherwise discontinued according to its terms, whereas surrender is a deliberate request by the policyholder to end the policy.
Does Term Insurance Have a Surrender Value?
This is one of the most important questions to understand. A basic pure-term insurance policy generally does not have a surrender value because it is designed primarily to provide life protection for a specified period rather than create a savings or investment component.
However, not every term product has identical features. Some term insurance plans may include a Return of Premium (ROP) option or other benefits under which a surrender value may be available according to the policy terms. So, don't assume that every term plan follows the same surrender rules.
Pure Term Plan- A pure term plan generally provides:
- Life cover for the selected policy term
- No maturity benefit if the insured survives the policy term, subject to the policy conditions
- No conventional savings component
- Generally no surrender value
Term Plan with Return of Premium- a Return of Premium term plan may return eligible premiums under specified circumstances. Depending on the product, surrender benefits may also be defined in the policy document.
For example, an insurer's current product document for a term plan with a Return of Premium option specifies surrender-value provisions after payment of the required premium period. This shows why the individual policy wording matters more than assuming one rule applies to every term plan.
Term Insurance Surrender Rules You Should Know
Before starting the surrender process, check these points:
1. Check the Type of Policy First identify whether you have a pure term plan, a Return of Premium term plan, or another life insurance product. The surrender treatment can differ significantly between these products.
2. Check Your Policy Document Your policy document should explain the conditions relating to surrender, discontinuation of premiums, paid-up status, and applicable benefits. Don't rely only on general information available online.
3. Check Whether a Surrender Value Is Available If your plan provides a surrender value, the policy document should explain how it is determined. The amount may depend on factors such as:
- Policy year
- Premiums paid
- Premium-paying term
- Policy term
- Type of benefits
- Applicable surrender-value formula
4. Understand That Surrender Ends the Cover Once your surrender request is processed, the policy's life cover ends according to the policy terms. Therefore, surrendering a policy is not simply a way to stop paying premiums.
5. Check the Financial Impact Before Cancelling If your policy has a surrender benefit, don't assume that you will receive all the premiums you have paid.
The amount payable can be substantially different from the total premium paid, depending on the product and stage of the policy.
How to Surrender Term Insurance?
The exact process can vary between insurers, but the usual process is straightforward.
Step 1: Review Your Policy Before submitting a request, check your policy document and understand:
- Current policy status
- Surrender eligibility
- Surrender value, if any
- Required documents
- Available alternatives
Step 2: Contact Your Insurer You can contact the insurer through its customer service channel, branch, website, or other permitted service channel. Ask specifically for the term insurance surrender process applicable to your policy.
Step 3: Submit the Surrender Request The insurer may ask you to complete a surrender or policy-service request form. Depending on the insurer and policy, you may need documents such as:
- Policy document
- Identity proof
- Address proof
- Bank account details
- Cancelled cheque or bank verification document
- Surrender request form
The exact document list can differ, so confirm it with your insurer.
Step 4: Insurer Verifies the Request The insurer checks your policy details and verifies the submitted information. If a surrender benefit is applicable, the insurer calculates the amount according to the policy terms.
Step 5: Receive the Applicable Amount If your policy provides a surrender value and the request meets the applicable conditions, the amount is paid according to the insurer's process.
If the policy does not have a surrender value, you should not expect a refund simply because you have paid premiums for several years.
How Is Term Insurance Surrender Value Calculated?
There is no single surrender-value formula that applies to every term insurance policy. Where a policy provides surrender value, the calculation depends on the product's terms.
Factors may include:
Factor | Why it matters |
Policy type | Different plans can have different surrender provisions |
Policy year | The benefit can vary depending on when you surrender |
Premiums paid | Some formulas use eligible premiums as a basis |
Premium-paying term | Can affect the applicable benefit |
Policy term | The surrender calculation may depend on the original term |
Product features | ROP or other benefits can change the calculation |
Policy conditions | The final amount follows the contract |
For this reason, don't use a generic online calculator to estimate your exact surrender amount unless it is based on your insurer's actual policy terms.
Is There a Term Insurance Surrender Charge?
A surrender charge is a deduction that may apply to certain insurance products when a policy is surrendered. However, you should not assume that a fixed surrender charge applies to every term insurance plan.
For a pure term plan, the bigger issue is usually whether the product has any surrender benefit at all.
If your plan has a surrender-value feature, check the policy document for:
- Surrender charges
- Applicable deductions
- Guaranteed surrender value
- Special surrender value
- Conditions for receiving the benefit
Your insurer can provide the applicable calculation for your specific policy.
Will You Get a Refund After Surrendering Term Insurance?
It depends on your policy.
If you have a basic pure-term plan You generally should not expect a refund of all the premiums you have paid simply because you surrender the policy. Those premiums were primarily paid for the life insurance protection provided during the period the policy was active.
If you have a Return of Premium or other eligible plan A surrender benefit may be available if the policy conditions are satisfied. The amount can depend on the policy year and the applicable surrender-value calculation. The safest way to know the exact amount is to request a surrender-value quotation from your insurer before cancelling the policy.
Surrender vs Lapse: What's the Difference?
These two terms are often confused.
Surrender | Lapse / Discontinuation |
You voluntarily request to end the policy | Policy may stop because required premiums are not paid |
The insurer processes a surrender request | The policy follows its non-payment provisions |
Any applicable surrender benefit is calculated according to policy terms | Any applicable revival or continuation options depend on policy conditions |
Life cover ends according to the policy terms | Life cover can be affected according to the policy conditions |
Simply stopping your premium payments is not the same as formally surrendering your policy.
Surrender vs Termination: Are They the Same?
Not always. Surrender Generally refers to the policyholder voluntarily requesting an early exit from a policy.
Termination Is a broader term describing the end of a policy contract. A policy can terminate for different reasons depending on its terms.
If you want to end your policy voluntarily, contact the insurer and ask specifically about the surrender procedure rather than assuming that stopping payments will automatically produce the same result.
Should You Surrender Your Term Insurance?
There is no single answer that applies to every policyholder. Before making a decision, ask yourself:
Do you still need financial protection? If your family, spouse, children, or other dependents still rely on your income, cancelling life cover can leave them without the protection the policy was intended to provide.
Has your financial situation changed? You may have changed jobs, paid off major liabilities, built sufficient assets, or experienced a significant change in your financial responsibilities.
These factors can affect how much life cover you need.
Can you replace the cover? If you are considering a new policy instead, don't surrender the existing cover until you understand the new policy's premium, eligibility, underwriting requirements, exclusions, and effective date.
A new policy is not guaranteed to be available on the same terms as an older policy.
Are you surrendering because of affordability? If premiums have become difficult to manage, ask the insurer whether any alternative options are available under your policy before cancelling it.
What Are the Alternatives to Surrendering Term Insurance?
Surrender may not always be the only option.
Depending on your policy, you may want to explore:
- Reviewing whether the current cover is still appropriate
- Checking whether the insurer offers any permitted policy alteration
- Understanding the consequences of stopping premiums
- Exploring whether another policy can meet your current requirements
- Reviewing your overall life insurance needs before making a change
The options available depend on the specific policy and insurer.
What Happens After Term Insurance Surrender?
Once the surrender is completed:
- The policy is ended according to its terms.
- The life cover under that policy stops.
- Any applicable surrender benefit is processed.
- Future premiums are no longer payable for that surrendered policy.
- The original policy generally cannot simply be treated as active again without following the insurer's applicable rules.
If you still need life insurance, consider your replacement coverage before surrendering the existing policy.
Free-Look Cancellation vs Term Insurance Surrender
Free-look cancellation and term insurance surrender are two different ways of ending a policy.
A free-look cancellation takes place shortly after you receive the policy documents, when you review the terms and decide that the policy does not meet your requirements. It is subject to the applicable free-look period and the conditions specified under the regulations and policy.
Surrender, on the other hand, generally refers to voluntarily ending the policy after it has been in force, subject to the policy's surrender provisions.
Free-Look Cancellation | Term Insurance Surrender |
Usually happens shortly after receiving the policy | Usually happens after the policy has been in force |
Used when you reconsider the policy after reviewing its terms | Used when you want to end the policy before its scheduled maturity |
Refund is subject to applicable deductions and conditions | Any surrender benefit depends on the policy terms |
Governed by applicable free-look provisions | Governed by the policy's surrender provisions |
Therefore, if you have only recently purchased the policy, check whether you are still within the applicable free-look period before considering surrender.
Can You Buy a New Term Plan After Surrendering?
Yes, you can generally apply for a new term insurance policy after surrendering an existing one. However, buying a new policy is a fresh application and is subject to the insurer's eligibility and underwriting requirements.
Your age, income, health information, lifestyle, policy requirements and other factors can affect the premium and terms offered by the new insurer.
If you are planning to replace your existing policy, don't surrender the old policy before confirming that the new policy has been approved and is active, if continuous life protection is important to you.
A new policy may also have different premiums and terms from your existing policy because it is being purchased at a later age and under the insurer's current underwriting rules.
Therefore, compare the new coverage carefully before completing a term insurance surrender.
FAQs
Can I surrender my term insurance policy?
Yes, you can request surrender where the policy permits it. However, whether you receive any surrender value depends on the type and terms of your policy.
Can I get my premium back after surrendering term insurance?
Not necessarily. A pure term plan generally does not provide a surrender value. Certain products, such as eligible Return of Premium plans, may provide a surrender benefit according to their terms.
Does pure term insurance have surrender value?
Generally, a basic pure-term plan does not accumulate a surrender value. Always check the specific policy document because product features can differ.
How do I surrender my term insurance policy?
Usually, you need to contact the insurer, submit the required surrender/service request and supporting documents, and complete the insurer's verification process.
What documents are required for term insurance surrender?
Requirements vary by insurer. Commonly requested documents may include the policy document, identity/address proof, bank details, and a completed surrender request form.
Is surrendering term insurance the same as stopping premium payments?
No. Surrender is a formal request to end the policy. Simply stopping premiums can cause the policy to lapse or otherwise change status according to the policy conditions.
Does surrendering term insurance affect my future insurance?
Surrendering an existing policy does not automatically prevent you from buying another policy, but a new application will be assessed under the new insurer's applicable underwriting and policy conditions.
Is term insurance surrender taxable?
The tax treatment can depend on the type of policy, premiums, benefits received, and applicable tax rules. Do not assume that every surrender payment receives the same tax treatment. For a significant amount, check the applicable tax rules or consult a qualified tax professional.

5.0
Need advice from experts?
Health is tricky, and insurance trickier. But we'll simplify it for you — for FREE! Book a call now. Limited slots available!
 Talk to an Advisor
 Talk to an Advisor