Term Insurance Death Claim
Term Insurance Death Claim
Term Insurance Death Claim is a request made by the nominee when the policyholder dies while the term insurance policy is active, allowing the nominee to receive the death benefit mentioned in the policy.
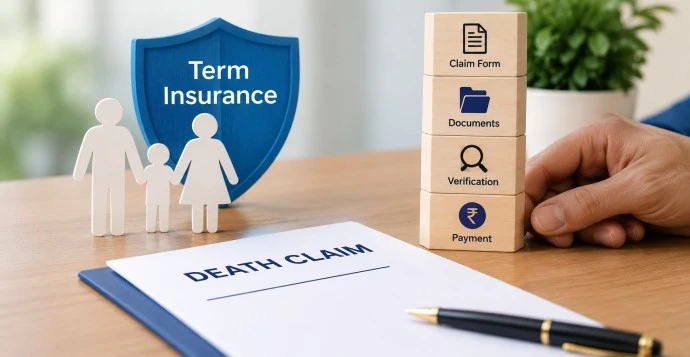
The basic process is straightforward: inform the insurer, submit the claim form and required documents, complete any verification or investigation, and wait for the insurer's claim decision and payment. The exact documents and process can vary depending on the insurer, policy and circumstances of death. For a family, knowing this process in advance can make things much easier when the claim actually needs to be filed.
What Is a Term Insurance Death Claim?
A term insurance death claim is a request made by the nominee or other legally entitled claimant to the insurance company after the death of the insured person. If the policy was active on the date of death and the claim is admissible under the policy terms, the insurer pays the applicable death benefit to the person legally entitled to receive it.
For example, suppose someone has a ₹1 crore term insurance policy and dies during the policy term. If the policy is active and the claim is accepted, the applicable death benefit is paid according to the policy terms.
A death claim is different from a maturity claim because a pure term insurance policy normally pays when the insured dies during the covered policy term rather than paying a maturity amount at the end.
Who Can Claim Term Insurance After the Policyholder's Death?
Usually, the nominee named in the policy initiates the death claim. Depending on the policy and legal circumstances, an assignee or legal heir may also have a role.
This is why keeping nominee details updated matters. The nominee should also know:
- The insurer's name
- Policy number
- Where the policy document is kept
- The policy's customer or claim contact details
- Which documents may be required
If the nomination is missing, disputed or does not clearly establish who is entitled to receive the policy money, the insurer may ask for additional evidence of legal title.
How to File a Term Insurance Death Claim?
The process generally follows these steps:
1. Inform the insurer about the death
The nominee should inform the insurer as soon as reasonably possible after the policyholder's death. The insurer will usually register the claim and explain the next steps and documents required.
2. Complete the death claim form
The claimant needs to submit the insurer's prescribed death claim form with accurate information about the policyholder, claimant and circumstances of death.
3. Submit the required documents
The claimant should provide the death certificate, policy details, identity and bank documents and other records requested by the insurer. The requirements can be different for natural and accidental deaths.
4. Verification or investigation
The insurer reviews the submitted information and may investigate the claim if the circumstances require it. This can involve checking medical records, policy details, the cause of death and other relevant information.
5. Claim decision
After assessment, the insurer will either approve the claim and arrange payment or communicate the reason for rejection/repudiation where the claim is not admissible.
What Documents Are Required for a Term Insurance Death Claim?
The exact list depends on the insurer and circumstances, but commonly requested documents may include:
- Death claim form
- Death certificate issued by the appropriate authority
- Original or copy of the policy document, where applicable
- Nominee's identity proof
- Nominee's address proof
- Nominee's bank account details
- Cancelled cheque or bank proof
- PAN/Form 60, where applicable
- Medical records or treatment documents, where required
- Proof of age, where required
- Hospital records or death summary, where applicable
For an accidental or unnatural death, the insurer may additionally ask for documents such as:
- FIR
- Police report
- Post-mortem report
- Panchanama/inquest report
- Final police report, where applicable
- Other records relating to the circumstances of death
Insurers can ask for additional documents when they are necessary to assess the claim.
What Is the Difference Between a Natural Death and Accidental Death Claim?
The basic claim process is similar, but the supporting documents can differ.
For a natural death, the insurer may ask for the death certificate, claim form, policy document and medical or hospital records where relevant.
For an accidental death, additional evidence may be required to establish how the accident happened. This can include an FIR, post-mortem report, police records and other documents.
So, an accidental death claim does not necessarily mean a completely different claim process. The main difference is usually the additional evidence needed to verify the circumstances of death.
How Long Does a Term Insurance Death Claim Take?
Under the current IRDAI policyholder-protection framework, death claims that do not require investigation are subject to a 15-day settlement timeline, while death claims requiring investigation are subject to a 45-day timeline, subject to the applicable regulatory conditions and receipt of the required claim information/documents.
The practical time taken can still vary depending on:
- Whether the documents are complete
- Whether additional information is required
- Whether the claim needs investigation
- Complexity of the circumstances of death
- Whether nominee or legal-title issues need clarification
So, a missing document or unresolved query can affect the overall process.
Why Are Term Insurance Claims Rejected?
Non-disclosure of important health information
If relevant medical information was not disclosed when the policy was purchased, it can become an issue during claim assessment. This is why policyholders should provide accurate information about their health, medical history, smoking or tobacco use and other information requested in the proposal form.
Incorrect information in the proposal form
Errors relating to age, occupation, income, lifestyle or other material information can create problems if the information was relevant to underwriting.
Policy lapse
Term insurance provides protection only according to the policy's terms and status. If premiums were not paid and the policy had lapsed before the death, the death benefit may not be payable. The grace-period rules in the policy are important here, so a missed premium should not automatically be treated as an immediate loss of cover.
Policy exclusions
The policy document contains the applicable exclusions and conditions. The claimant should check these rather than relying on general information found online.
Fraud or deliberate misrepresentation
Intentional concealment or fraudulent information can have serious consequences for a death claim.
What Is the Suicide Clause in Term Insurance?
Many term insurance policies contain a specific provision relating to suicide during an initial period of the policy or after revival.
The exact benefit and conditions depend on the policy wording.
This is an area where it is better not to rely on a generic statement such as “suicide means no claim.” The applicable policy document should be checked because the provision may specify a particular benefit or treatment of the claim.
What Is Section 45 of the Insurance Act and Why Does It Matter?
Section 45 of the Insurance Act, 1938 deals with when a life insurance policy can be called into question on grounds such as fraud or material misstatement/suppression.
It is often discussed in relation to death claims because families may wonder whether an insurer can question an old policy based on information provided when the policy was purchased.
However, Section 45 contains specific statutory conditions and should not be reduced to a simple statement such as “after three years every claim is guaranteed.”
The actual circumstances, applicable law, policy documents and nature of the issue matter.
For this reason, nominees should obtain the insurer's written reason if a claim is repudiated and review the decision against the policy and applicable law.
Can a Nominee File a Term Insurance Claim Online?
Many insurers provide online or email-based claim intimation and document submission facilities, although the exact process differs between insurers. Some claims may still require physical documents, verification or additional records.
So, the practical answer is Yes, a term insurance death claim may be initiated online with many insurers, but the complete claim process depends on the insurer and the circumstances of the death.
The nominee should use the insurer's official claim channel rather than sending sensitive documents to an unknown third party.
How Can You Check Term Insurance Claim Status?
After registering the claim, the nominee can generally check its status through the insurer's website, app, and customer service or claims department, depending on the facilities offered.
Keep these details handy:
- Policy number
- Claim number
- Registered mobile number
- Claimant details
- Date of claim intimation
The claim may move through stages such as registration, document review, investigation, decision and settlement.
If the insurer asks for additional documents, responding promptly can help avoid unnecessary delays.
What Happens If the Term Insurance Claim Is Delayed?
First, find out why the claim is delayed.
Check whether:
- Any document is missing
- The insurer has raised a query
- Investigation is pending
- Nominee details need clarification
- Bank details need correction
- Legal-title documents are required
If the insurer does not resolve the issue satisfactorily, the claimant can use the insurer's grievance-redressal mechanism. IRDAI's Bima Bharosa platform also provides a route for registering insurance complaints.
What Happens to the Term Insurance Payout After Claim Approval?
Once the death claim is approved and the insurer completes the required payment formalities, the applicable death benefit is paid to the person legally entitled to receive it under the policy and applicable law. The amount payable depends on the policy terms and the death benefit selected.
For example, if the policy provides a ₹1 crore death benefit and the claim is admissible, the applicable benefit will be paid according to the policy terms.
The actual payout should always be checked against the policy document rather than assuming that the advertised cover amount is automatically payable in every situation.
What If the Nominee Is a Minor?
If the nominee is a minor, the process can involve an appointee or other legally appropriate arrangement depending on how the nomination was made and the applicable rules. This is another reason why policyholders should review nominee details after major life events such as marriage, childbirth or changes in family circumstances.
What If the Policyholder Dies Outside India?
A death outside India can require additional documentation.
Depending on the insurer and circumstances, documents may include the foreign death certificate, passport/visa records, local police documents, proof of burial or cremation and other records. The nominee should contact the insurer's claims team as early as possible to obtain the exact requirements.
Some insurers specifically provide separate document requirements for deaths occurring outside India.
How to Make a Term Insurance Death Claim Easier for Your Family
A few simple steps can prevent a lot of confusion later.
- Keep the policy document safely: Your family should know where it is stored.
- Keep nominee details updated: Marriage, divorce, childbirth or other family changes may require nomination updates.
- Tell your family about the policy: A policy cannot help if the family does not know that it exists.
- Keep important medical records: They may be useful if the insurer requests them during claim assessment.
- Pay premiums on time: Check the policy status and do not ignore missed-premium notices.
- Keep proposal information: The information provided when buying the policy can become relevant during claim assessment.
- Keep bank details updated: Correct claimant bank information can help avoid payment-related delays.
Term Insurance Death Claim vs Term Insurance Maturity Claim
| Term Insurance Death Claim | Term Insurance Maturity Claim |
| Filed after the life insured dies during the policy term | Relevant only where the policy provides a maturity benefit |
| Usually filed by nominee/legal claimant | Usually payable to the policyholder or applicable beneficiary |
| Requires death-related documents | Requires maturity-related documents |
| Death benefit is paid if the claim is admissible | Maturity benefit depends on the policy terms |
For a pure term insurance policy, the main purpose is generally protection against death during the policy term.
FAQs
The nominee should inform the insurer, submit the death claim form and required documents, cooperate with any verification or investigation, and wait for the claim decision.
The death benefit is generally paid to the nominee or other person legally entitled to receive the policy proceeds, depending on the nomination and applicable legal circumstances.
Common documents include the claim form, death certificate, policy details, nominee KYC and bank details. Accidental deaths may require FIR, post-mortem and other police documents.
Under the current regulatory framework, death claims not requiring investigation have a 15-day settlement timeline, while claims requiring investigation have a 45-day timeline, subject to the applicable requirements.
Yes. Claims can be rejected or repudiated when the claim is not payable under the policy terms or applicable law, including issues involving material non-disclosure, fraud, policy status or applicable exclusions.
Yes, an accidental death can be covered if the policy is active and the death falls within the policy terms. The insurer may request additional accident-related documents such as an FIR and post-mortem report.
The exact treatment depends on the policy terms. The grace-period provisions should be checked rather than assuming that the policy immediately loses all protection after the premium due date.
Having a medical condition does not automatically make a death claim invalid. What matters includes what was disclosed when the policy was purchased, the policy terms and the circumstances of the claim.
The insurer may require additional documents to establish who is legally entitled to receive the policy proceeds. The nominee should contact the insurer and provide the requested evidence.
Many insurers allow claim intimation or document submission through online channels, but the complete process varies by insurer and claim circumstances.
Ask the insurer for the written reason for rejection, review it against the policy and proposal documents, and use the insurer's grievance-redressal process if you want the decision reviewed
A lost policy document does not necessarily mean that a claim cannot be filed. Contact the insurer with the policy number and claimant details and ask for the exact documentation required.

5.0
Need advice from experts?
Health is tricky, and insurance trickier. But we'll simplify it for you — for FREE! Book a call now. Limited slots available!
 Talk to an Advisor
 Talk to an Advisor